All Categories
Featured

Securing Coverage to Support Families
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, but it's readily available to employers of all sizes and has no contribution limits.
But, they should have a qualifying type of individual health coverage to get involved. Companies can set different allowances based upon staff member classes for added personalization. Group coverage HRA (GCHRA): Likewise called an integrated HRA, a GCHRA is for companies of any size who offer a group health strategy. Only workers enrolled in their company's group strategy can participate.
While they have no maximum contribution limits, the internal revenue service does not enable compensations for monthly premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can help staff members spend for their out-of-pocket medical costs and, sometimes, their medical insurance premiums. An HRA is a popular alternative choice over traditional health benefits because they're economical for companies and versatile enough for every employee.

Current Term Life Insurance Rates for Families
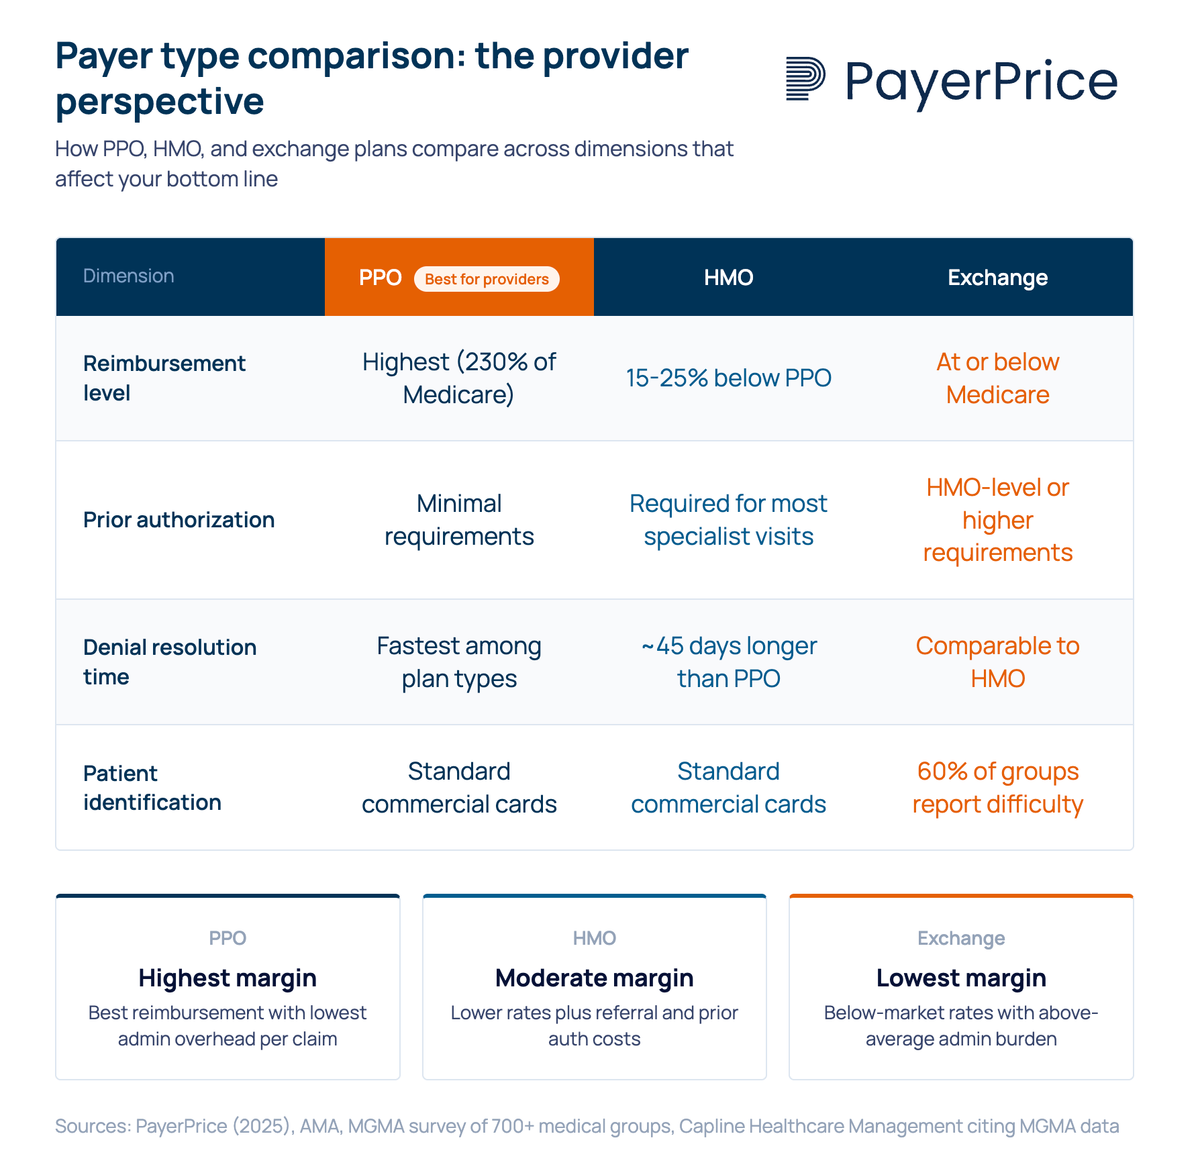
An HMO might be your finest bet if you're looking for a plan with a low premium. Nevertheless, a PPO plan provides additional versatility if you require more control over your healthcare. That's why researching these plans carefully, including their pros, cons, and average costs, is the very best very first action you can take in the past making a choice.

Latest Posts

Medicare Part D Enrollment Guide

Why Seniors Choose Final Expense Insurance Coverage
Securing Coverage to Support Families